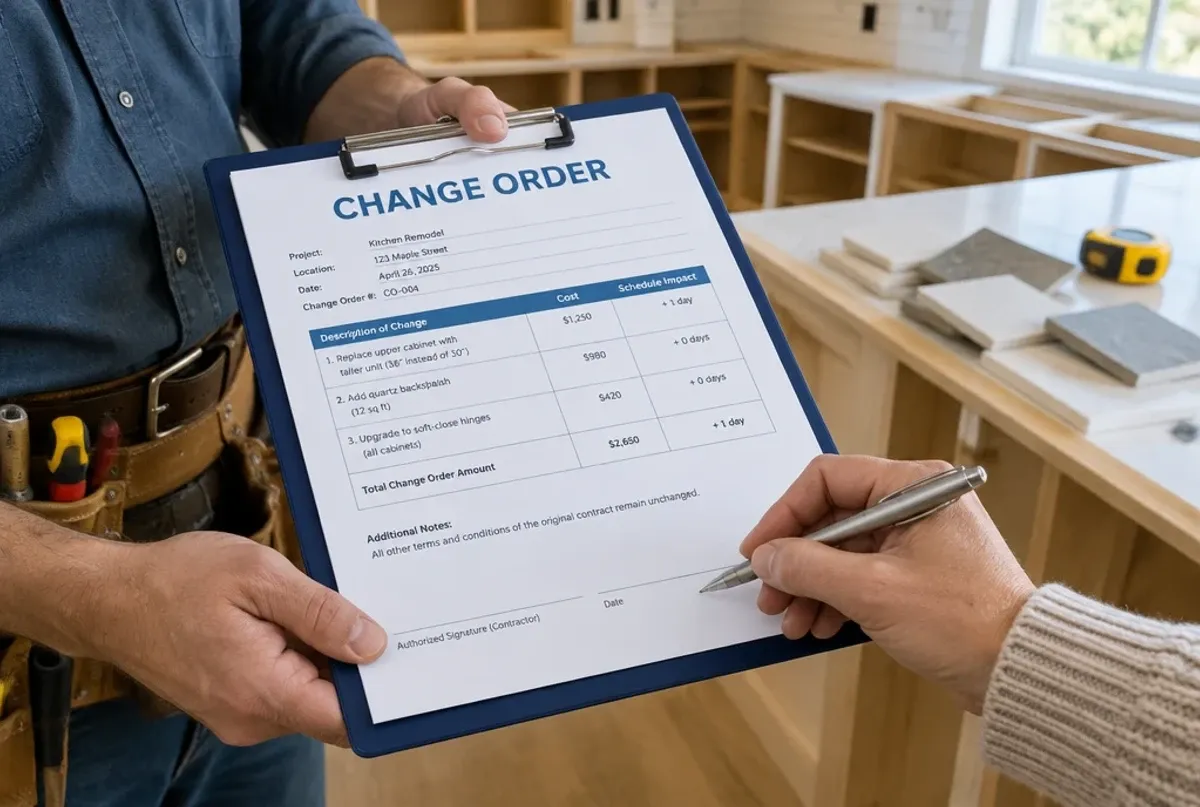
Every price you quote has to cover two kinds of cost. Variable costs change with each job: the materials, the hours on site, a subcontractor, a dumpster. Fixed costs arrive every month whether you work or not: insurance, the truck payment, your phone, software, your accountant. Price only the first kind and you lose money on jobs that looked profitable.
This lesson shows you how to list both, how to turn your fixed costs into a number per billable hour, and how to price the time customers don’t see: prep, travel and the small jobs that eat a day.
Variable costs: what each job costs you
These belong to one job. List them for every job you price:
| Cost | What to count | Easy to forget |
|---|---|---|
| Labor | Your hours on the job, plus any helper’s hours | Prep, cleanup and the second visit |
| Materials | Everything installed or used up | Waste, consumables (blades, bits, caulk, tape), delivery fees, sales tax, the trip back for what was missing |
| Subcontractors | Any trade you bring in | Their price for coming back |
| Job-specific extras | Equipment rental, disposal, permits, parking | Fees that only show up on this job |
If you hire help, their real cost is more than their wage: payroll taxes, workers’ compensation and other costs come on top, and not every hour you pay them is an hour you can bill. Price their hours from that real cost, not from the wage. How to calculate your labor burden rate walks through it with a worksheet.
Fixed costs: what the business costs every month
These don’t belong to any one job, so they’re easy to leave out of every price. Fill in this table with your own numbers; for anything paid yearly, divide by 12:
| Monthly fixed cost | Example | Yours |
|---|---|---|
| Insurance | $250 | |
| Vehicle payment and insurance | $650 | |
| Fuel and vehicle maintenance (monthly average) | $400 | |
| Phone and internet | $120 | |
| Software (estimates, scheduling, bookkeeping) | $100 | |
| Accountant or bookkeeper | $150 | |
| Licenses, renewals and dues (yearly ÷ 12) | $50 | |
| Marketing (website, profile, cards) | $150 | |
| Tool replacement fund | $200 | |
| Storage, shop space or an equipment loan | $530 | |
| Total overhead per month | $2,600 |
Example numbers, not typical costs. Your list will differ by trade and area. Fuel rises with the number of jobs, but starting out it’s simpler to keep a monthly average here and add a travel line to quotes for far-away jobs. Your own pay is not on this list: it gets its own line below, so it’s counted once.
Turn overhead into a number per billable hour
Customers pay per job, but overhead arrives per month. To get it into your prices, spread it over the hours you can actually bill:
Example: overhead per billable hour
Overhead: $2,600 a month × 12 = $31,200 a year.
Billable hours: 4 job days × 7 hours on the job × 44 working weeks = 1,232 hours a year. Count only hours on the job, after holidays, sick days and slow weeks.
Overhead per billable hour: $31,200 ÷ 1,232 = about $25.
Add your own pay and a profit the same way, and you have your hourly target:
| Per billable hour | Yearly amount | ÷ 1,232 hours |
|---|---|---|
| Overhead | $31,200 | $25.32 |
| Your pay, before taxes | $50,000 | $40.58 |
| Profit (for slow months, new equipment, growth) | $8,800 | $7.14 |
| Hourly target | $90,000 | about $73 |
Every hour you bill below about $73 in this example is an hour that doesn’t fully pay its share. Your pay here is before taxes: set part of every payment aside for income and self-employment tax, and ask your accountant how much. Materials and subcontractors are priced on top, per job, with your markup: markup vs. margin shows how.
Count the time the customer doesn’t see
A painting job isn’t only the hours with a roller in your hand.
Example: an interior room repaint
Painting walls and ceiling: 6.5 hours. Prep (moving and covering furniture, masking, filling holes, sanding, spot-priming): 3 hours. Cleanup and walkthrough: 1 hour.
Labor hours on the job: 10.5, not 6.5.
At $73 an hour, labor is about $767. Pricing only the painting gives about $475: $292 short on one room.
The drive doesn’t go in the hourly count. Your time on the road is covered because your pay is spread over billable hours, and fuel is in overhead; a far-away job gets a travel line.
Example numbers.
Write down the prep and cleanup you actually do on each kind of job, and use it every time you price. Then put it in writing for the customer: how to build a construction estimate shows what to include.
Small jobs cost more per hour
Every job comes with time you can’t bill, whatever its size: the estimate visit, the supplier run, invoicing and following up. Your hourly target assumes a set amount of it, for example one office day a week. Many small jobs blow through that.
Example: the same billable week, two ways
Per-job time you can’t bill: estimate visit 1 h, supplier run 1 h, invoicing 0.5 h = 2.5 hours per job.
Four one-day jobs: 28 billable hours, 4 × 2.5 = 10 hours of per-job time. Roughly fits the 7-hour office day plus a little overtime.
Eight half-day jobs: the same 28 billable hours, but 8 × 2.5 = 20 hours of per-job time. That’s a 48-hour week for the same pay, or fewer billable hours and less pay.
Example numbers.
Three fixes; pick at least one and write it into your pricing rules:
- A minimum job charge, for example at least half a day of labor plus materials, whatever the job.
- A trip or setup charge on every job, which covers the visit, the supplier run and the drive.
- A higher hourly rate for small jobs than for jobs of a day or more.
Check your numbers against what really happened
Your first estimates are guesses. After each job, write down the actual hours (including prep, cleanup and return visits), the actual materials and any surprise costs, next to what you estimated. After five or ten jobs, your prep times, material waste and small-job hours come from your own records instead of hope. Construction job costing shows how to compare estimated and actual costs job by job.
Your next action
This week:
- Fill in the monthly fixed-cost table with your own numbers and get your monthly overhead.
- Divide your yearly overhead by your billable hours to get your overhead per billable hour.
- Take your last job and list every variable cost, including prep, cleanup, waste and the supplier runs.
- Decide on a minimum job charge or a setup line for small jobs, and write it down.
FAQ
What is overhead for a contractor?
Every cost of running the business that doesn’t belong to a single job: insurance, the vehicle and fuel, phone, software, accounting, licenses, marketing, tool replacement and storage. Your prices have to cover it, usually as an amount per billable hour, on top of your own pay.
Is labor a fixed or a variable cost?
It depends whose labor. A helper paid by the hour only when there’s work is a variable cost of each job. Someone on a fixed salary is a fixed cost, paid whether jobs come in or not. For a one-person business, your own pay works like a fixed cost: you need it every month, so count it in your hourly target.
What is the difference between fixed and variable costs in construction?
Variable costs rise and fall with the work: materials, job labor, subcontractors, rentals and disposal. Fixed costs stay roughly the same each month whether you have work or not: insurance, vehicle payments, software and similar bills. Price variable costs per job, and spread fixed costs over your billable hours.
See your real costs in MotionOps
MotionOps is field service software for contractors that records costs as the job runs: Field Expense Tracking and AI Receipt Capture for materials and purchases, and Job Costing, which compares each job’s revenue with its actual labor and material costs.
See all features or compare plans. When you’re ready for your first jobs, try MotionOps free.